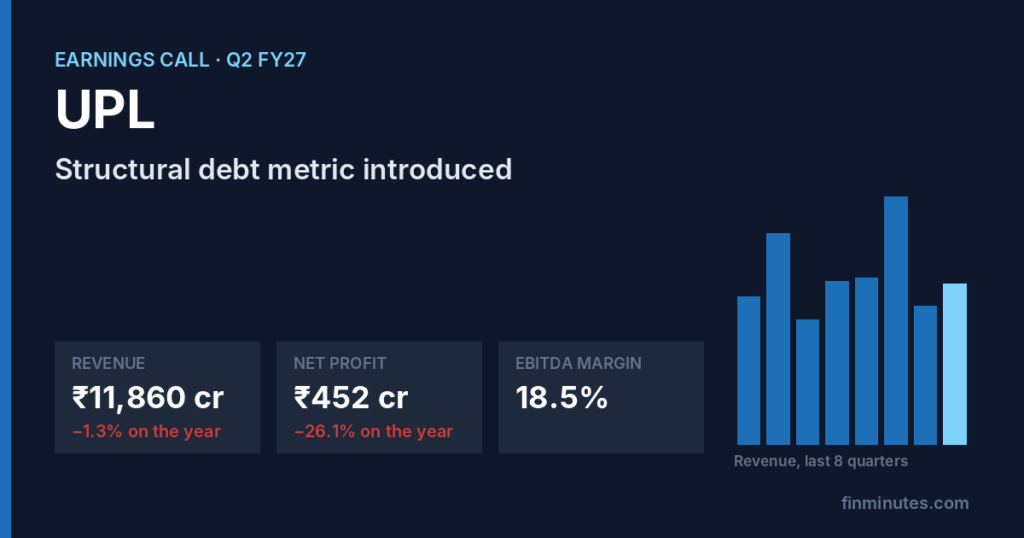
UPL delivered Q2 FY27 revenue of ₹11,860 crore (-1% YoY) and H1 FY27 revenue of ₹22,041 crore (+4% YoY), supported by double-digit growth in Advanta (+12%) and Superform (+28%) which cushioned a 16% volume drop in global crop protection (UPL Corp). Operational net profit reached ₹422 crore in Q2, driven by an eighth consecutive quarter of EBITDA margin expansion (+120 bps to 19.5%) and SG&A cost optimization. However, operating cash flow was constrained as net working capital expanded by 27 days to 145 days, pushing reported net debt to ~$3 billion. UPL mitigated refinancing risk by extending $400 million of debt to FY32. What remains unresolved is the working capital unwinding trajectory in LATAM and the final timeline for the corporate reorganization scheme.
The numbers behind this call, with every quarter on the same rules: UPL Q2 FY27 results.
What the call was about
- Corporate Reorganization, Governance & Statutory Auditor Transition (3 questions). Reorganization disclosures will be made as regulatory milestones occur; LIC board nomination strengthens governance; EY replacing KPMG upon 10-year rotation across all group entities.
- Balance Sheet, Working Capital Expansion & Structural Debt Metric (3 questions). Prepaid $500M Dec 2026 debt and extended $400M to FY32; structural debt is ~$800M while reported net debt fluctuates with seasonal working capital.
- Platform Performance, Cost Optimization & Operational One-Offs (3 questions). Superform and Advanta delivered strong double-digit growth; GBS expansion reduced employee costs; ₹75 crore VAT reversal and ₹57 crore settlement are operational.
- Global Crop Protection, Chinese Price Escalation & El Niño Impact (3 questions). Glufosinate and generic Chinese price hikes will benefit margins as channel inventory clears; navigating El Niño through biostimulants and differentiated products.
Structural debt metric introduced
- UPL introduced structural debt (net debt less net working capital) at ~$800 million representing 0.7x gearing
- Reported net debt rose to ~$3 billion due to $312 million working capital and capex expansion
- Prepaid $500 million term loan maturing December 2026 and refinanced $400 million to FY32
Glufosinate prices rebound
- Chinese glufosinate and technical active ingredient prices rising due to strict environmental compliance
- Higher realizations will reflect in Americas once low-cost channel inventory liquidates
- Superform specialty chemicals volume grew 33% driven by contract manufacturing
Advanta egypt seed acquisition
- Advanta agreed to acquire 99.98% of Misr Hytech Seed International in Egypt for ~$110 million
- Expands tropical field corn and sorghum footprint across Middle East and North Africa
- Advanta H1 revenue grew 18% to ₹3,629 crore with EBITDA up 21% to ₹868 crore
In management’s words
UPL delivered its eighth consecutive quarter of improvement in margins and EBITDA grew 5% in the quarter and 9% in the first half with margins expanding by 120 and 80 basis points.
concall, transcript p.3
Advanta, our seeds and post-harvest platform, has agreed to acquire 99.98% of Misr Hytech Seed International in Egypt for approximately $110 million.
concall, transcript p.7
S&P revised the outlook on UPL Corp to positive from stable affirming its BB rating and CRISIL revised the outlook on UPL Limited to stable affirming its AA+ and A1+ ratings.
concall, transcript p.8
Of the $500 million term loan maturing in December 2026, we have refinanced $400 million to FY32, well ahead of the schedule.
concall, transcript p.8
We reported revenue of 11,860 crore, stable at 1% lower than last year. Volumes declined by 10%, pricing was flat and currency contributed a positive 9%.
concall, transcript p.8
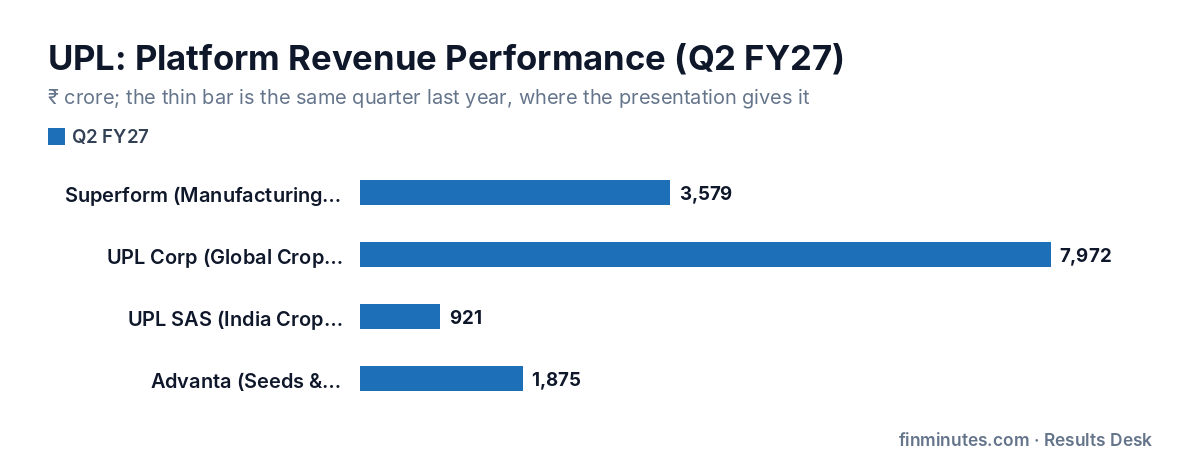
Superform grew revenue by an outstanding 28% to 3,579 crore with pricing up 26% and volumes up 2%.
concall, transcript p.13
What the company says drove the quarter
- Consolidated Q2 FY27 Revenue (₹11,860 crore, -1% YoY) down: 10% volume decline in global crop protection offset by 9% positive currency contribution and double-digit growth in Advanta and Superform.
- Consolidated Q2 FY27 EBITDA (₹2,312 crore, +5% YoY) up: Margin expansion of 120 bps to 19.5% from improved product/platform mix, brand strength, and SG&A cost optimization.
- Superform Revenue Q2 FY27 (₹3,579 crore, +28% YoY) up: Driven by 50% growth in specialty chemicals (33% volume, 17% price) and active ingredient price pass-through (+21%).
- Superform EBIT Q2 FY27 (₹323 crore, +39% YoY) up: Driven by price realization, higher share of specialty chemicals (29% vs 25%), and strong lubricant contract manufacturing.
- UPL Corp Q2 FY27 Revenue (₹7,972 crore, -8% YoY) down: Impacted by 16% volume decline and 2% price decline due to tight LATAM grower credit, European heatwave, and cautious buying.
- Advanta Q2 FY27 Revenue (₹1,875 crore, +12% YoY) up: Driven by field corn in Argentina, LATAM, and Indonesia, sunflower and grain sorghum in Argentina, and post-harvest growth.
- UPL SAS H1 FY27 EBITDA (₹553 crore, +20% YoY) up: Driven by 430 bps margin expansion to 26.8% from 9% price realization and 80% growth in hyper-scale brands.
- Net Working Capital Days Q2 FY27 (145 days, +27 days YoY) up: Driven by a 16-day increase in inventory days from higher input costs, lower crop volumes, and H2 inventory build-up.
Guidance
| Metric | Guidance | For | Against earlier guidance |
|---|---|---|---|
| Revenue Growth Guidance | 7.00–11.00 % | FY2027 | was maintained (reconfirmed comfortable with guidance) |
| EBITDA Growth Guidance | 10.00–14.00 % | FY2027 | was maintained (reconfirmed comfortable with guidance) |
| Net Debt to EBITDA Target | 1.50–1.50 x | Medium-term | was maintained |
| Capex and Growth Investment Guidance | 425.00 | FY2027 | was maintained |
Forward numbers as management gave them. FinMinutes checks each one against the quarter it was meant for.
Where analysts pushed
| Question | Answer | Answered? |
|---|---|---|
| Are you going ahead with the corporate reorganization scheme or open to reworking it given negative market perception? | Management stated they cannot comment on this call but will update the market in accordance with listing obligations if there are material developments. | Deflected |
| Why is LIC nominating a director on the board at this time? | LIC is a long-term shareholder and NRC felt bringing senior LIC expertise in finance/risk enhances overall board governance; timing should not be misconstrued. | Yes |
| Are the ₹75 crore VAT provision reversal and ₹57 crore corporate settlement one-off items that should be in exceptional? | VAT reversal was an operational working capital provision reversal, and the ₹57 crore settlement was an operational take-or-pay contract termination fee. | Yes |
| When will higher Chinese glufosinate and technical prices reflect in higher realizations in Americas markets? | Price increases will take effect in Americas once lower-cost channel inventory liquidates during the ongoing season. | Yes |
| What was the factoring amount this quarter and what is the net debt and capex guidance? | Factoring was ~$70 million lower YoY; capex and growth investment guidance remains $425 million, with medium-term net debt to EBITDA target at 1.5x. | Partly |
| Why did employee expenses decline 15% YoY in Q2? | Driven by GBS transition (headcount up 3x across lower-cost hubs in Pune, Colombia, Mauritius), target operating model cost savings, and FX devaluation. | Yes |
Plans, launches and capacity
- Acquisition of Misr Hytech Seed International in Egypt: 99.98% stake for ~$110 million (Q2 FY2027), under way
- Term Loan Refinancing to FY32: $400 million refinanced out of $500 million December 2026 maturity (Q2 FY2027), completed
- Global Business Services (GBS) Capacity Expansion: Headcount expanded 3x across Pune, Colombia, and Mauritius centers (H1 FY2027), completed
- Superform Specialty Chemicals Contract Manufacturing Commercialization: Specialty volume up 33%, platform EBIT up 39% to ₹323 crore (Q2 FY2027), under way
From the investor presentation
Platform Revenue Performance (Q2 FY27) (₹ crore)
| This quarter | YoY | |
|---|---|---|
| Superform (Manufacturing & Specialty Chemicals) | 3579.00 | +28.0% |
| UPL Corp (Global Crop Protection) | 7972.00 | −8.0% |
| UPL SAS (India Crop Protection) | 921.00 | +1.0% |
| Advanta (Seeds & Post-Harvest) | 1875.00 | +12.0% |
Source: transcript p.13, 14, 16, 18
Platform EBITDA / EBIT Performance (Q2 FY27) (₹ crore)
| This quarter | YoY | |
|---|---|---|
| Superform EBIT | 323.00 | +39.0% |
| UPL Corp EBITDA | 1083.00 | — |
| UPL SAS EBITDA | 214.00 | +3.0% |
| Advanta EBITDA | 510.00 | +19.0% |
Source: transcript p.14, 16, 17, 19
First Half (H1 FY27) Platform Performance (₹ crore)
| This quarter | YoY | |
|---|---|---|
| Advanta H1 Revenue | 3629.00 | +18.0% |
| Advanta H1 EBITDA | 868.00 | +21.0% |
| UPL Crop H1 Revenue | 14345.00 | −2.0% |
| UPL SAS H1 EBITDA | 553.00 | +20.0% |
Source: transcript p.16, 17, 19
Tone against the last call
Management shifted from focusing solely on reported net debt reduction targets to introducing 'structural debt' ($800 million / 0.7x gearing) to explain working capital expansion.
What is still open
- When will regulatory approvals and shareholder voting for the corporate reorganization scheme be completed? (answer expected in: Regulatory exchange filings and statutory meeting notices)
- Will net working capital days normalize back toward ~120 days by FY27 year-end? (answer expected in: Q3 FY27 financial results and investor presentation)
- What are the key financial terms (revenue and EBITDA multiples) for the Misr Hytech acquisition upon closing? (answer expected in: Post-closing press release or Q3 FY27 concall transcript)
- How quickly will Chinese glufosinate and technical AI price hikes translate into higher realizations in LATAM and US markets? (answer expected in: Q3 FY27 platform performance commentary for UPL Corp and Superform)
Frequently asked questions
What did UPL management say on the Q2 FY27 call?
UPL delivered Q2 FY27 revenue of ₹11,860 crore (-1% YoY) and H1 FY27 revenue of ₹22,041 crore (+4% YoY), supported by double-digit growth in Advanta (+12%) and Superform (+28%) which cushioned a 16% volume drop in global crop protection (UPL Corp). Operational net profit reached ₹422 crore in Q2, driven by an eighth consecutive quarter of EBITDA margin expansion (+120…
What guidance did UPL give?
Revenue Growth Guidance: 7.00–11.00 % for FY2027.
Is this a recommendation?
No. FinMinutes reports what was filed and said, and the questions it raises. It does not recommend buying, selling or holding any security.
The full UPL Q2 FY27 results page →
The UPL terminal →
Quotes are verbatim from the transcript, presentation or press release named beside them. FinMinutes is a financial data and analytics platform; nothing here is a recommendation to buy, sell or hold any security.

Leave a Reply