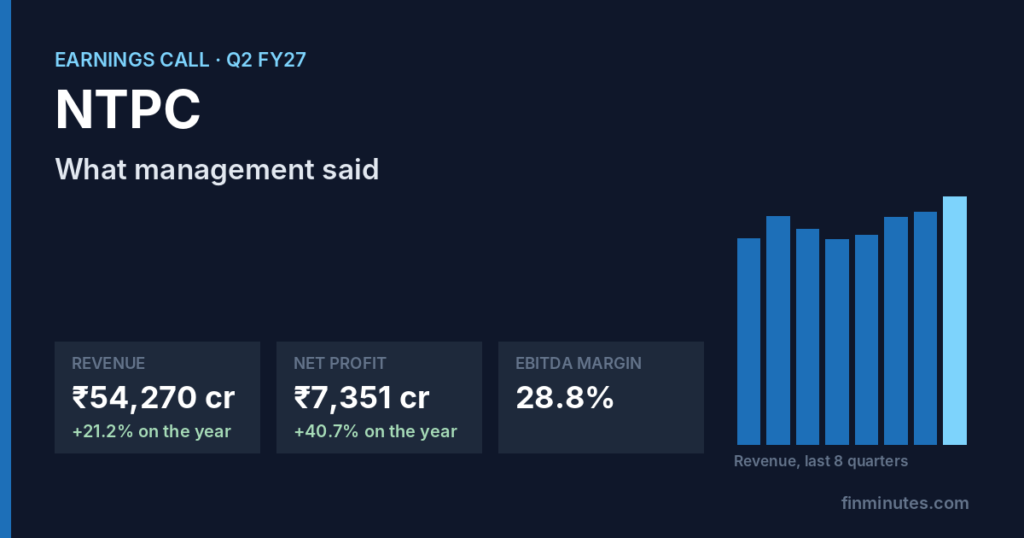
NTPC delivered strong Q2 FY27 operational performance, driven by an 11% national power generation growth that boosted standalone revenue 17% YoY to ₹45,752 crore and PAT 14% YoY to ₹5,320 crore. Consolidated PAT jumped 26% YoY to ₹14,247 crore in H1 FY27, bolstered by subsidiary contributions of ₹3,194 crore. Operating cash flows remained robust with captive coal dispatches rising 21% to 26.13 MMT and average borrowing costs easing to 5.72%. However, transmission bottlenecks in the Khavda region pushed commercial commissioning of ~1.5 GW renewable capacity to November 2027, scaling down FY27 RE additions to ~6.35 GW. Unresolved issues include execution timelines for 40 GWh BESS procurement and grid curtailments affecting NGEL’s immediate revenue realization.
The numbers behind this call, with every quarter on the same rules: NTPC Q2 FY27 results.
What the call was about
- Renewable Capacity Addition Targets & Transmission Curtailment (3 questions). Transmission constraints in Khavda/Rajasthan delayed commercial commissioning to Nov 2027, but on-ground capacity construction remains on track at 6.35 GW for FY27.
- Battery Energy Storage Systems (BESS) & Procurement Strategy (2 questions). Deploying 40 GWh BESS via direct international competitive bidding (ICB) following GFR Rule 144 relaxation to address solar backing down and evening ramps.
- Thermal Tendering Pipeline & Capacity Additions (2 questions). Tendering 4,800 MW thermal capacity in Q1-Q2 FY28 with ₹67,000 crore capex alongside 17.32 GW currently under construction.
- Subsidiary & JV Profitability (THDC, Ratnagiri, BRBCL) (2 questions). Higher market power sales at Ratnagiri, full capacity impact at THDC Kurja, and debt refinancing at BRBCL drove strong subsidiary profit contributions.
BESS direct Chinese procurement
- NTPC obtained government relaxation under GFR Rule 144 to directly import Chinese battery cells
- Issuing a 40 GWh International Competitive Bidding (ICB) tender for utility-scale battery storage
- Implementing 5 GW BESS at thermal power plant locations to balance grid ramps
Transmission delay cuts RE target
- NGEL RE capacity COD target for FY27 scaled down from 8 GW to ~6.35 GW on-ground erection
- Khavda transmission line completion pushed from October 2026 to November 2027
- Curtailment impact mitigated as PPA tenor extends and TGNA covers operational expenses
Thermal capacity expansion wave
- NTPC expanding thermal pipeline with 4,800 MW new tendering across Q1-Q2 FY28 worth ₹67,000 crore capex
- Lara Stage 3 (3,600 MW) awarded and moved under active construction bringing total under-construction capacity to 17.32 GW
- Offering 26% equity to C&I clients under group captive route for thermal power and process steam
In management’s words
NTPC group generation stood at 213.6 billion unit in H1 FY27 compared with 214 billion in H1 FY26 registering growth of 10.4%.
concall, transcript p.10
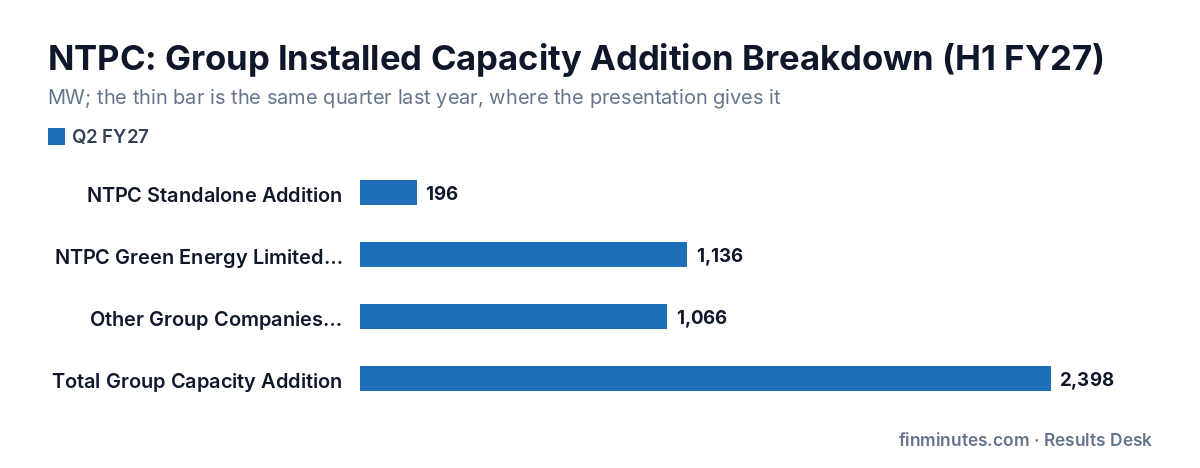
As on H1 FY27, NTPC groups installed capacity stood at 91,566 megawatt. We have added 2,398 megawatt of capacity.
concall, transcript p.9
Our coal stations achieved a PLF of 75.11% against rest of India’s average of 68.35%.
concall, transcript p.10
We have incurred a group capex of 23,932 crore in H1 FY27 as compared to rupees 23,150 crore in H1 FY26.
concall, transcript p.12
Moving ahead we have plans for tendering out close to 4.8 gigawatt further… with estimated capex of 67,000 crores.
concall, transcript p.19
We are already implementing 5 GW of battery energy storage system at our thermal power stations alongside pursuing other long-duration storage opportunities.
concall, transcript p.5
What the company says drove the quarter
- Standalone Revenue from Operations Q2 FY27 (₹45,752 crore, +17% YoY) up: Driven by robust demand growth in national power generation (+11%) and peak demand (+15%), enabling higher thermal commercial generation.
- Standalone Net Profit Q2 FY27 (₹5,320 crore, +14% YoY) up: Driven by operational efficiency gains and substantial drop in fixed cost under-recovery/disincentive to ₹332 crore from ₹625 crore in prior year.
- Consolidated Net Profit H1 FY27 (₹14,247 crore, +26% YoY) up: Supported by subsidiary net profit contribution of ₹3,194 crore and group share of JV profits of ₹1,253 crore.
- NGEL Revenue from Operations Q2 FY27 (₹938.16 crore, +53.22% YoY) up: Driven by a 60% surge in renewable power generation to 10.88 BU in H1 FY27 alongside fresh operational capacity additions.
- Standalone Other Income Q2 FY27 (dropped by ₹432 crore) down: Impacted by lower dividend receipts from JV/subsidiaries (-₹481 crore) and a 28% decline in Late Payment Surcharge (LPS) due to better collection efficiency.
- Captive Coal Mine Dispatches H1 FY27 (26.13 MMT, +21% YoY) up: Enabled by superior monsoon preparedness at captive coal mines and optimized coal loading infrastructure planning.
- Weighted Average Borrowing Cost H1 FY27 (5.72% vs 5.98% in FY26) down: Benefited from proactive loan refinancing, restructuring, and low-cost IFSC gift city USD loan/RBI swap facility execution.
- BRBCL Subsidiary Profit Q2 FY27 (+₹64 crore YoY) up: Attributable to reduction in finance cost following debt refinancing/scheduled principal repayments and fly-ash transportation billing.
Guidance
| Metric | Guidance | For | Against earlier guidance |
|---|---|---|---|
| FY27 Group Capacity Addition Target | 6350–8000 MW | FY2027 | was Initial guidance of 9000 MW scaled down to ~8000 MW (~6.35 GW on-ground COOD + transmission delays) |
| FY28 Group Capacity Addition Target | 9639–9639 MW | FY2028 | was maintained (1460 MW thermal, 444 MW hydro, 7735 MW RE) |
| FY29 Group Capacity Addition Target | 10877–10877 MW | FY2029 | was maintained (3000 MW thermal, 7877 MW RE) |
| Thermal Tendering Pipeline | 4800 | FY2028 | was 4800 MW thermal capacity tendering planned across standalone and JVs with estimated capex of ₹67,000 crore |
| Battery Energy Storage System (BESS) Procurement | 40000 | FY2028 | was 40 GWh direct ICB tender for BESS procurement planned |
Forward numbers as management gave them. FinMinutes checks each one against the quarter it was meant for.
Where analysts pushed
| Question | Answer | Answered? |
|---|---|---|
| Why is RE capacity addition guidance being scaled down, and how much revenue loss occurred due to transmission curtailment? | Transmission connectivity in Rajasthan/Gujarat is delayed until November 2027; ~6.35 GW is being erected on ground for FY27 while ~1.5 GW awaits transmission COOD. Tariff TGNA covers operational expenses, and PPA tenor gets extended so full revenue is shifted rather than lost. | Partly |
| Why did standalone PAT grow 14% YoY despite standalone regulated equity dropping and Other Income falling by ₹432 crore? | Profitability growth was driven by operational efficiency gains, higher plant generation, and a drop in fixed cost disincentives/under-recoveries to ₹332 crore from ₹625 crore in prior year. | Yes |
| What drove the sharp profit jump at Ratnagiri Gas & Power and THDC during the quarter? | Ratnagiri profits rose due to high market power generation sales during peak demand, while THDC benefited from full capacity operationalization of Kurja 660 MW thermal and 500 MW PSP units. | Yes |
| What are the capacity addition targets across thermal and RE for FY28 and FY29? | FY28 target is 9,639 MW (1,460 MW thermal, 444 MW hydro, 7,735 MW RE) and FY29 target is 10,877 MW (3,000 MW thermal, 7,877 MW RE). | Yes |
| Why do RE addition timelines consistently get pushed back on ground? | On-ground construction remains on track at 6.35 GW, but official commercial operation date (COOD) is delayed due to PGCIL Khavda transmission line completion shifting from October 2026 to November 2027. | Yes |
| Why does setting up BESS take 12-18 months, and can NTPC procure battery cells directly from Chinese suppliers instead of going through intermediaries? | Previously Rule 144 GFR restricted direct Chinese procurement. Management obtained government relaxation and is issuing a direct 40 GWh ICB tender allowing direct sourcing from Chinese suppliers. | Yes |
Plans, launches and capacity
- Green Energy Corridor Phase 3 Scheme Approval: Outlay of ₹1,86,450 crore with central support of ₹54,820 crore to evacuate 135 GW RE and 50 GWh storage by FY33 (2026-09-30), announced
- C&I Group Captive Equity Stake Offering: EOI issued for 26% equity participation by C&I consumers for coal power generation and heat (Q2 FY2027), announced
- Lara Stage 3 Project Award & LNTP: 3600 MW capacity awarded with limited notice to proceed issued (Q2 FY2027), under way
- Offshore USD Syndicated Loan Facility: USD 750 million facility executed with SBI/HDFC/BOB IFSC Gift City; USD 450 million drawn with RBI swap (2026-05-06), completed
- Data Center Business Entry Phase 1: Setting up 100 MW data center capacity across initial locations (H1 FY2027), under way
- Synthetic Natural Gas (SNG) Coal Gasification Project: Proposal submitted under Ministry incentive scheme for 5 lakh tonnes per annum SNG plant at Talipali (H1 FY2027), announced
From the investor presentation
Group Installed Capacity Addition Breakdown (H1 FY27) (MW)
| This quarter | YoY | |
|---|---|---|
| NTPC Standalone Addition | 196.00 | — |
| NTPC Green Energy Limited (NGEL) Group Addition | 1136.00 | — |
| Other Group Companies Addition | 1066.00 | — |
| Total Group Capacity Addition | 2398.00 | — |
Source: transcript p.9
Power Generation and Trading Volumes (H1 FY27) (BU)
| This quarter | A year ago | YoY | |
|---|---|---|---|
| NTPC Group Total Generation | 213.60 | 214.00 | −0.2% |
| NGEL Group Generation | 10.88 | 6.76 | +61.0% |
| NVVN Traded Power Volume | 31.00 | 24.80 | +25.0% |
Source: transcript p.10
Captive Coal Production & Dispatches (H1 FY27) (MMT)
| This quarter | A year ago | YoY | |
|---|---|---|---|
| Coal Dispatched from Group Captive Mines | 26.13 | 21.63 | +20.8% |
Source: transcript p.11
What is still open
- Will the Khavda transmission corridor be commissioned by the revised deadline of November 2027 without further delay? (answer expected in: Q3/Q4 FY27 investor presentation and PGCIL/CEA transmission monitoring reports)
- What will be the winning tariff and vendor selection for the upcoming 40 GWh direct ICB BESS tender? (answer expected in: NGEL exchange disclosures and Q3 FY27 concall transcript)
- How many commercial and industrial (C&I) partners will participate in the 26% group captive thermal equity offering closing in November 2026? (answer expected in: Q3 FY27 earnings presentation and exchange filings)
- When will the land acquisition and Final Approval for Mahi Banswara nuclear project be completed? (answer expected in: Annual Report FY27 / Future concall management commentary)
Frequently asked questions
What did NTPC management say on the Q2 FY27 call?
NTPC delivered strong Q2 FY27 operational performance, driven by an 11% national power generation growth that boosted standalone revenue 17% YoY to ₹45,752 crore and PAT 14% YoY to ₹5,320 crore. Consolidated PAT jumped 26% YoY to ₹14,247 crore in H1 FY27, bolstered by subsidiary contributions of ₹3,194 crore. Operating cash flows remained robust with captive coal dispatches rising 21%…
What guidance did NTPC give?
FY27 Group Capacity Addition Target: 6350–8000 MW for FY2027.
Is this a recommendation?
No. FinMinutes reports what was filed and said, and the questions it raises. It does not recommend buying, selling or holding any security.
The full NTPC Q2 FY27 results page →
The NTPC terminal →
Quotes are verbatim from the transcript, presentation or press release named beside them. FinMinutes is a financial data and analytics platform; nothing here is a recommendation to buy, sell or hold any security.


Leave a Reply