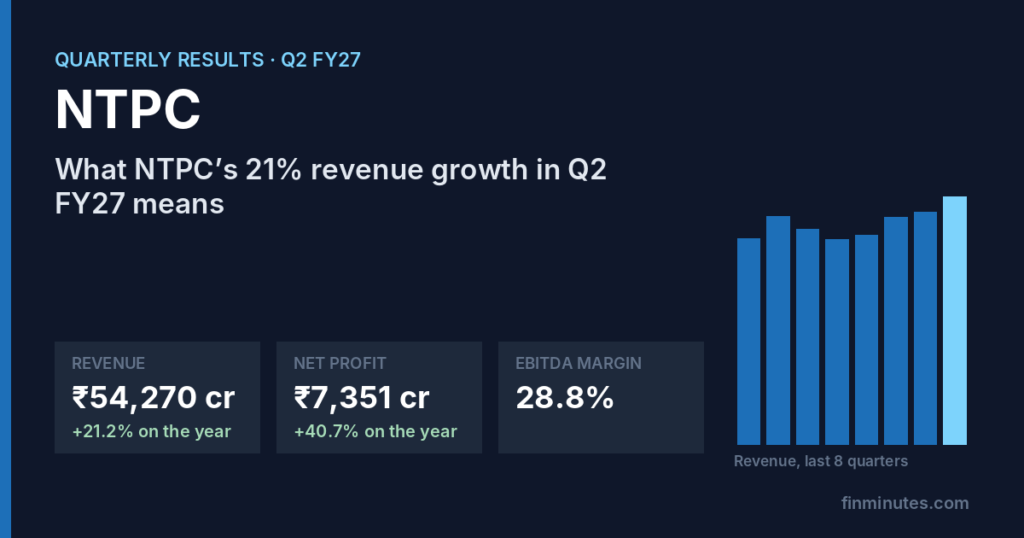
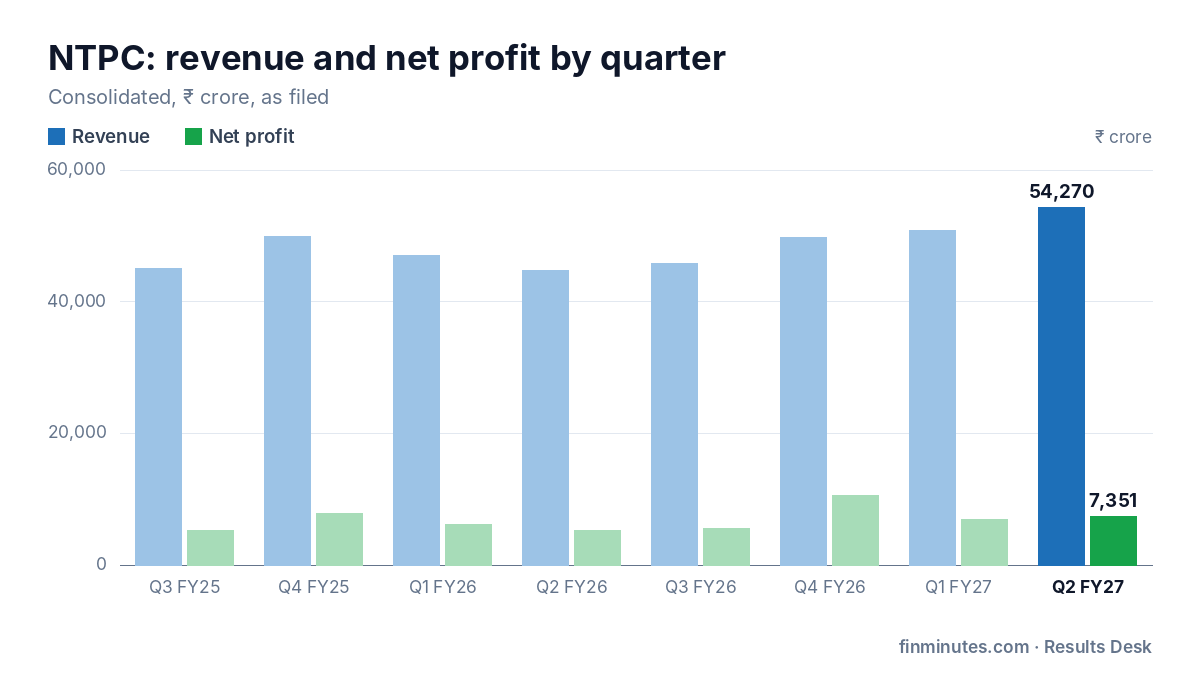
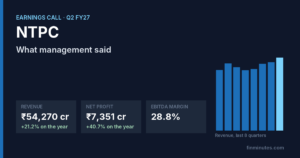
NTPC Ltd. reported revenue of ₹54,270 cr for July to September 2026, +21.2% on the year and +7.0% on the quarter. That is faster than this quarter has grown in recent years (−0.2% on average), so the year-on-year number is not just the season. It is the highest quarterly revenue in the last 12 quarters on record. Over the last four quarters revenue comes to ₹2.01 lakh cr, +7.4% on the four before.
The full NTPC Q2 FY27 results page carries every quarter on the same rules, the checks that ran and the ones that need the filing read: NTPC Q2 FY27 results, read forensically.
NTPC Q2 FY27: the numbers
| Sep '26 | Previous quarter | A year ago | On the year | |
|---|---|---|---|---|
| Revenue | ₹54,270 cr | ₹50,741 cr | ₹44,784 cr | +21.2% |
| EBITDA | ₹15,627 cr | ₹16,231 cr | ₹12,814 cr | +22.0% |
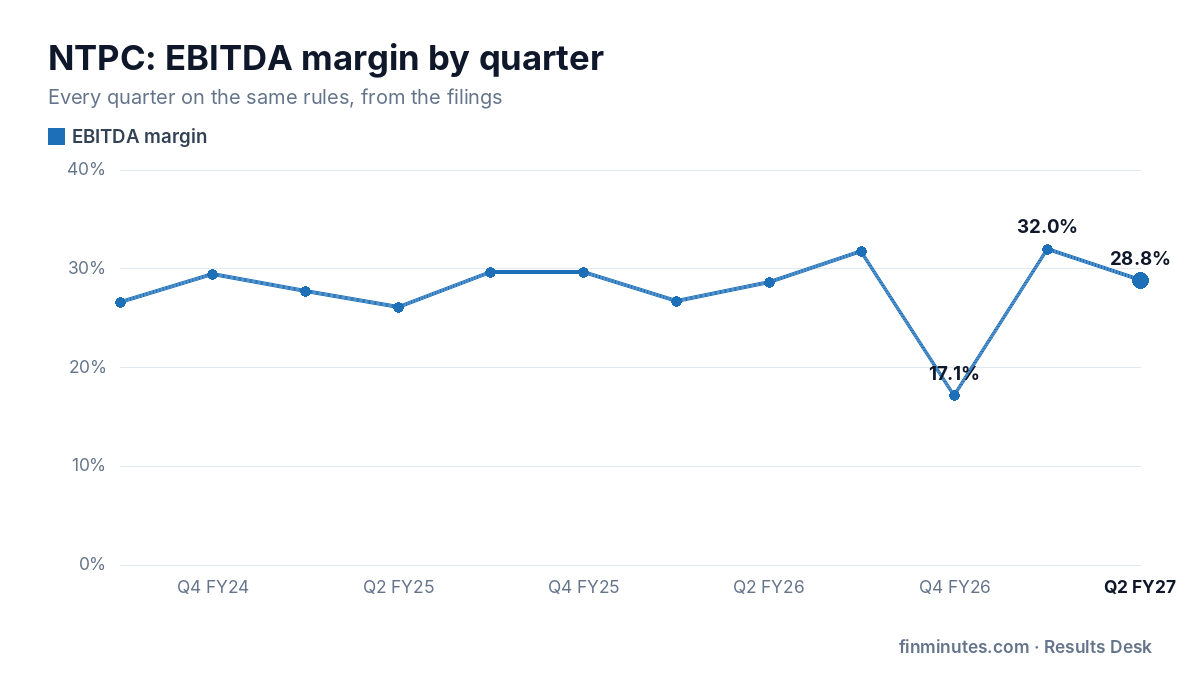
| EBITDA margin | 28.8% | 32.0% | 28.6% | +18 bps |
| Net profit | ₹7,351 cr | ₹6,896 cr | ₹5,225 cr | +40.7% |
| EPS | ₹7.25 | ₹6.93 | ₹5.23 | +38.6% |
Consolidated figures in ₹ crore, as filed with the exchanges.
What the numbers say
Operating profit (EBITDA) was ₹15,627 cr, a margin of 28.8%, +18 bps on the year and −319 bps on the quarter. Over the last 8 quarters the margin has ranged from 17.1% to 32.0%, averaging 28.0%. Operating costs grew +20.9%, broadly with revenue, so operating profit kept pace with sales.
Net profit was ₹7,351 cr, +40.7% on the year and +6.6% on the quarter, with earnings per share of ₹7.25. Profit before other income, one-offs and tax grew 32.8%, so 8 points of the headline growth came from outside the core business. The tax rate of 26% is in line with its recent average. Profit over the last four quarters totals ₹30,459 cr, +24.8% on the four before.
Of the 4 companies in Power and utilities that have reported Q2 FY27 so far, NTPC Ltd. ranks 2nd on revenue growth; the sector median is +8.6%. Its margin moved +18 bps on the year against a sector median of +114 bps.
NTPC Ltd. is a Nifty 50 company. Of the 17 Nifty 50 companies reported so far, the median profit growth is +16.5%; NTPC Ltd.'s +40.7% puts it above that.
Most power earnings are regulated returns on equity, with fuel costs passed through, so revenue can swing with fuel prices while profit moves far less.
On earnings per share of ₹30.65 over the last four quarters, the stock at ₹314.10 trades at 10.2 times trailing earnings.
Where the profit change came from
Net profit went from ₹5,225 cr in Sep '25 to ₹7,351 cr in Sep '26. Taking each line in turn: Business (EBITDA) added ₹2,813 cr, depreciation took away ₹514 cr, finance cost took away ₹654 cr, other income took away ₹32.3 cr, tax added ₹209 cr and other lines added ₹304 cr.
What the company says drove it
- Standalone Revenue from Operations Q2 FY27 (₹45,752 crore, +17% YoY) up: Driven by robust demand growth in national power generation (+11%) and peak demand (+15%), enabling higher thermal commercial generation.
- Standalone Net Profit Q2 FY27 (₹5,320 crore, +14% YoY) up: Driven by operational efficiency gains and substantial drop in fixed cost under-recovery/disincentive to ₹332 crore from ₹625 crore in prior year.
- Consolidated Net Profit H1 FY27 (₹14,247 crore, +26% YoY) up: Supported by subsidiary net profit contribution of ₹3,194 crore and group share of JV profits of ₹1,253 crore.
- NGEL Revenue from Operations Q2 FY27 (₹938.16 crore, +53.22% YoY) up: Driven by a 60% surge in renewable power generation to 10.88 BU in H1 FY27 alongside fresh operational capacity additions.
- Standalone Other Income Q2 FY27 (dropped by ₹432 crore) down: Impacted by lower dividend receipts from JV/subsidiaries (-₹481 crore) and a 28% decline in Late Payment Surcharge (LPS) due to better collection efficiency.
- Captive Coal Mine Dispatches H1 FY27 (26.13 MMT, +21% YoY) up: Enabled by superior monsoon preparedness at captive coal mines and optimized coal loading infrastructure planning.
- Weighted Average Borrowing Cost H1 FY27 (5.72% vs 5.98% in FY26) down: Benefited from proactive loan refinancing, restructuring, and low-cost IFSC gift city USD loan/RBI swap facility execution.
- BRBCL Subsidiary Profit Q2 FY27 (+₹64 crore YoY) up: Attributable to reduction in finance cost following debt refinancing/scheduled principal repayments and fly-ash transportation billing.
Segments
| Segment | Revenue | YoY | Result | YoY |
|---|---|---|---|---|
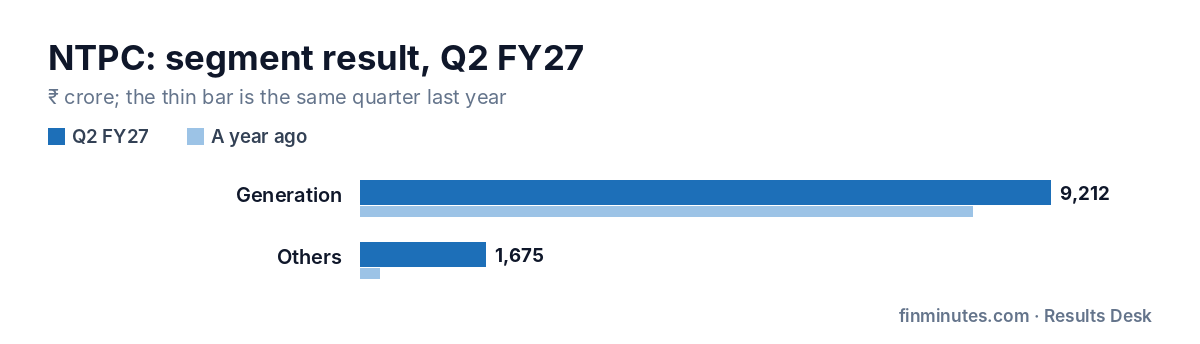
| Generation | ₹53,258 cr | +22.4% | ₹9,212 cr | +12.7% |
| Others | ₹7,349 cr | +49.3% | ₹1,675 cr | +543.4% |
The operating numbers
Group Installed Capacity Addition Breakdown (H1 FY27) (MW)
| This quarter | YoY | |
|---|---|---|
| NTPC Standalone Addition | 196.00 | — |
| NTPC Green Energy Limited (NGEL) Group Addition | 1136.00 | — |
| Other Group Companies Addition | 1066.00 | — |
| Total Group Capacity Addition | 2398.00 | — |
Source: transcript p.9
Power Generation and Trading Volumes (H1 FY27) (BU)
| This quarter | A year ago | YoY | |
|---|---|---|---|
| NTPC Group Total Generation | 213.60 | 214.00 | −0.2% |
| NGEL Group Generation | 10.88 | 6.76 | +61.0% |
| NVVN Traded Power Volume | 31.00 | 24.80 | +25.0% |
Source: transcript p.10
Questions the numbers raise
None of the 16 checks that could run on this quarter raised a question. That says the numbers cleared these checks; it is not a verdict on the company.
How it compares with Power and utilities this season
| Company | Revenue growth | Margin change | Profit growth |
|---|---|---|---|
| Adani Energy Solutions Ltd. | +52.8% | +114 bps | +144.9% |
| NTPC Ltd. | +21.2% | +18 bps | +40.7% |
| Indian Energy Exchange Ltd. | +8.6% | −213 bps | +12.9% |
| Jaiprakash Power Ventures Ltd. | +5.1% | +1,070 bps | −81.9% |
What to watch next
For a company in Power and utilities, the numbers to watch are plant load factor, capacity added and regulated equity.
The next quarter, Q3 FY27, has to be filed by 14 Feb 2027. The same checks will run on it, and the results page will compare it with this one.
All of NTPC's quarters, the checks and the profit bridge →
The NTPC terminal: financials, valuation history and forensic checks →
Frequently asked questions
What were NTPC Ltd. Q2 FY27 results?
NTPC Ltd. reported revenue of ₹54,270 cr (+21.2% on the year) and net profit of ₹7,351 cr (+40.7% on the year) for July to September 2026.
Was NTPC Ltd. profit growth driven by the core business?
Profit before other income, exceptional items and tax moved +32.8% on the year, against +40.7% for reported profit.
Are there any red flags in NTPC Ltd. Q2 FY27 results?
None of the 16 checks that could run raised a question.
Is this a recommendation?
No. FinMinutes reports what was filed and the questions the numbers raise. It does not recommend buying, selling or holding any security.
Numbers as filed with the exchanges, read by published rules. FinMinutes is a financial data and analytics platform; nothing here is a recommendation to buy, sell or hold any security.


Leave a Reply