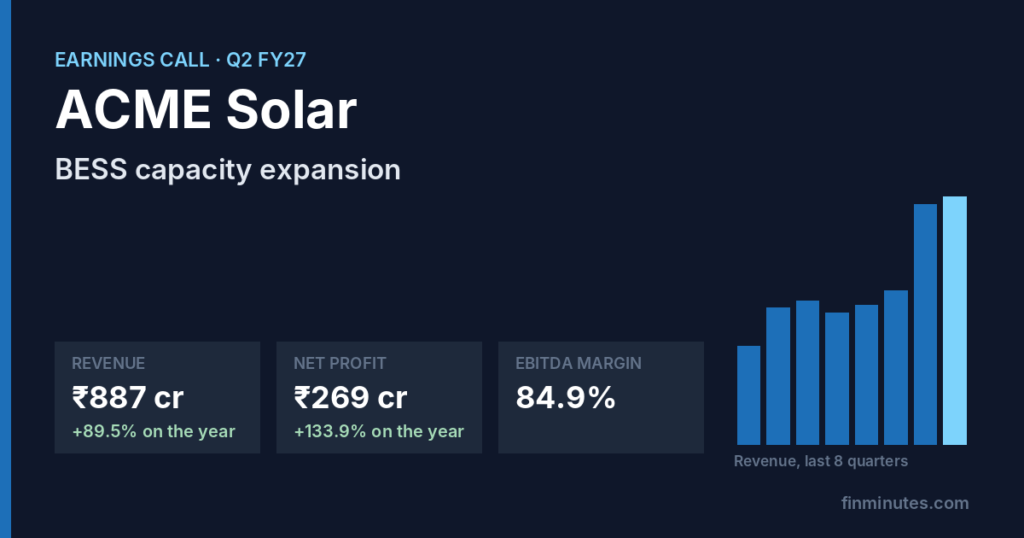
Acme Solar Holdings delivered strong operational performance in Q2 FY27, with total revenue rising 67.5% YoY to ₹1,007 crore and EBITDA expanding 63.6% YoY to ₹874 crore at an 86.7% margin. Net profit increased 133.5% YoY to ₹269 crore. Growth was driven by short-term BESS peak power monetization and 19.6% higher generation output (1,840 MU). BESS capacity reached 5.2 GWh, prompting management to raise FY27 commissioning guidance to >12 GWh and lock in over ₹1,600 crore in FY27 revenue. Cash flows remain backed by QIP funds and BESS accruals. However, full plant commissionings remain constrained by GNA transmission grid delays, forcing reliance on partial commissioning and BESS co-location, while exact H2 capex cadence and final NTPC PPA tariff adjustments remain key open monitorables.
The numbers behind this call, with every quarter on the same rules: ACME Solar Holdings Q2 FY27 results. Our read of the quarter itself: ACME Solar Q2 FY27 results: revenue up 90%, and what is behind it.
What the call was about
- Capex, Debt Accounting, and Financial Metrics (6 questions). H2 capex will be higher with ₹6,500 cr already executed, while early debt drawdowns for BESS front-ended capex explain balance sheet movements.
- BESS Strategy, Tariffs, and Revenue Lock-in (5 questions). BESS operates as a cash machine with >₹1,600 cr locked in for FY27 and >₹1,500 cr for FY28, replacing RTC power in state tenders.
- Capacity Addition, GNA Transmission Delays, and 2030 Targets (5 questions). Transmission delays are bypassed by deploying BESS at operational GNA substations, supporting 1.5 GW solar COD in FY27 and 15 GW by 2030.
- PPA Contracting, Bidding Environment, and Module Procurement (4 questions). SECI bids are closely mapped to state demand with faster PPA execution within 2 months, and module prices remain well within budgeted levels.
BESS capacity expansion and revenue lock-in
- FY27 BESS commissioning target raised to >12 GWh with 5.2 GWh commissioned to date.
- Locked in >₹1,600 cr revenue for FY27 and >₹1,500 cr for FY28 through short-term peak power contracts.
- 2030 BESS target doubled to 50 GWh alongside 15 GW renewable capacity.
GNA transmission delays and early deployment strategy
- Deployment strategy shifted to installing BESS at operational GNA substations to bypass transmission grid delays.
- Partially commissioned 1.9 GW contracted capacity, utilizing curtailed solar power to charge batteries.
- Targeting 1.5 GW full commissioning in FY27 and 2.5-3.0 GW in FY28.
Profitability growth and financial performance
- Q2 FY27 EBITDA increased 63.6% YoY to ₹874 cr with an EBITDA margin of 86.7%.
- PAT rose 133.5% YoY to ₹269 cr driven by short-term BESS operations.
- Weighted average cost of operational debt maintained at 8.4% with 65% held by long-term state institutions.
In management’s words
FI27 best commissioning guidance raised from 10 gawatt hour to more than 12 gawatt hour driven by our early deployment strategy
concall, transcript
by 2030 our renewable target rises from 10 gawatt with 25 gawatt hour of best to 15 gawatt and 50 gawatt hour of battery
concall, transcript
Through short-term breast contracts, we have locked in more than 1,600 cr of revenue for partial sale of FI27 capacity and more than 1,500 cr for partial sale of capacity for FI28
concall, transcript
we are targeting to capitalize whole of 12 gawatt hour of best in this calendar in this financial year only
concall, transcript
in FY28 in terms of the GNA availability we are looking at upwards of 3 GW around 2 and a half to 3 GW
concall, transcript
What the company says drove the quarter
- EBITDA Growth (+63.6% YoY) +63.6%: Driven primarily by short-term peak power BESS operations and renewable capacity additions.
- CUF Improvement (from 24.1% to 27.8% YoY) +3.7%: Addition of 150 MW wind capacity operating at 41% CUF, plant repowering, and operationalization of Sikar plant.
- Power Generation Growth (up 19.6% YoY) +19.6%: Higher CUF across operational solar assets, plant repowering, and contribution from 150 MW wind capacity.
- Flat Interest Cost QoQ 0%: Debt paydown using ₹2,800 cr QIP proceeds, internal BESS cash flows reducing debt drawdowns, and refinancing dollar bonds into lower-rate rupee debt.
- PAT Growth (+133.5% YoY) +133.5%: Revenue expansion from short-term BESS peak power monetization combined with controlled interest costs.
Guidance
| Metric | Guidance | For | Against earlier guidance |
|---|---|---|---|
| BESS Commissioning Target | >12 GWh | FY2027 | was 10 GWh |
| Renewable Generation Target | 15 GW | 2030 | was 10 GW |
| Battery Storage Target | 50 GWh | 2030 | was 25 GWh |
| Full Generation Capacity Addition | 1.5–1.5 GW | FY2027 | unchanged or first given |
| Partial Generation Capacity Addition | 2.5–3 GW | FY2027 | unchanged or first given |
| Generation Capacity Addition | 2.5–3 GW | FY2028 | unchanged or first given |
Forward numbers as management gave them. FinMinutes checks each one against the quarter it was meant for.
Where analysts pushed
| Question | Answer | Answered? |
|---|---|---|
| Clarification on capex execution and H2 outlook versus earlier ₹15,000-17,000 cr expectation. | Management clarified that ₹6,500 cr capex is done in H1 and H2 capex will be higher due to 5 GWh pending battery deliveries and module installations. | Yes |
| Concern over gap between gross block increase (₹1,782 cr) and operational debt increase (₹3,100 cr). | Management explained early debt drawdowns for front-ended BESS capex before LC opening and capitalization. | Yes |
| Feasibility of 15 GW 2030 target amidst transmission and GNA connectivity delays. | Management stated targeted substations have timelines up to 2028-2029 and existing connectivity is sufficient. | Yes |
| Return math on recent 400 MW NTPC PPA at ₹6/kWh tariff given high battery cost. | Management highlighted early commissioning returns by deploying BESS on operational GNA substations prior to solar COD. | Yes |
Plans, launches and capacity
- BESS Capacity Commissioning: 5.2 GWh commissioned to date, FY27 target raised to >12 GWh (FY2027), under way
- FDR PPA Signing with NTPC: 400 MW signed yesterday; total PPA portfolio reached 92% of 8,370 MW (Q2 FY2027), completed
- Short-term Peak Power BESS Contracting: Locked in >₹1,600 cr for FY27 and >₹1,500 cr for FY28 (FY2027-FY2028), under way
- Capex Outlay and Capitalization: ₹6,500 cr spent in H1 (₹3,500 cr capitalized, ₹3,000 cr CWIP); H2 capex expected to be higher to capitalize 12 GWh BESS (H1 FY2027), under way
From the investor presentation
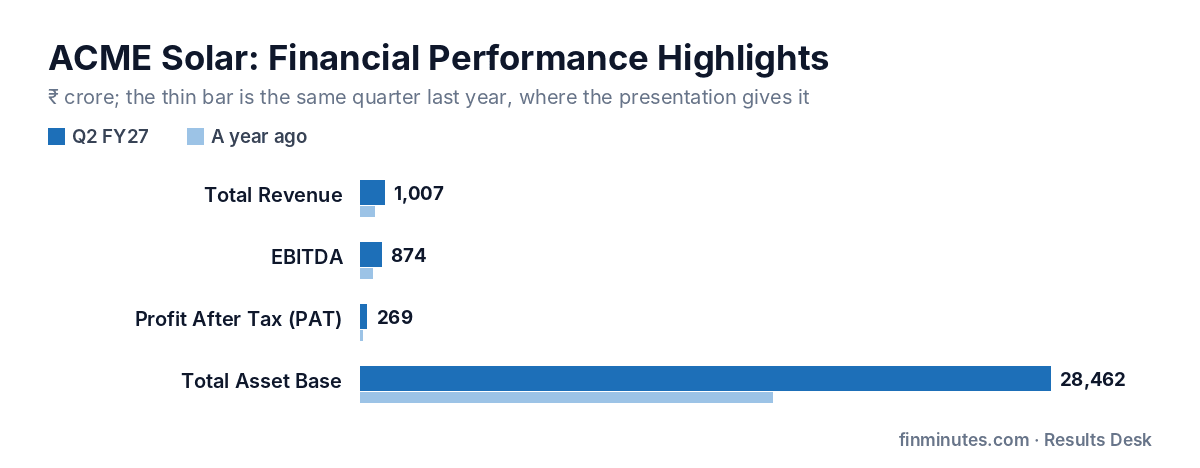
Financial Performance Highlights (₹ crore)
| This quarter | A year ago | YoY | |
|---|---|---|---|
| Total Revenue | 1007 | 601 | +67.5% |
| EBITDA | 874 | 534 | +63.6% |
| Profit After Tax (PAT) | 269 | 115 | +133.5% |
| Total Asset Base | 28462 | 16996 | +67.5% |
Source: transcript
Operational & BESS Metrics (various)
| This quarter | A year ago | YoY | |
|---|---|---|---|
| Power Generation (MU) | 1840 | 1538 | +19.6% |
| BESS Short-term Power Sold (MU) | 324 | — | — |
| Blended CUF (%) | 27.8 | 24.1 | — |
| Commissioned BESS Capacity (GWh) | 5.2 | — | — |
| Partially Commissioned Capacity (GW) | 1.9 | — | — |
Source: transcript
EBITDA Margin Breakdown by Segment (percent)
| This quarter | YoY | |
|---|---|---|
| Blended EBITDA Margin | 86.7 | — |
| Renewable Generation EBITDA Margin | 90.8 | — |
| BESS Operations EBITDA Margin | 78.3 | — |
Source: transcript
Tone against the last call
Management shifted focus from pure capacity addition numbers (megawatts) to revenue generation capability, return on capital, and self-financing cash flow generation through BESS deployment.
What is still open
- Historical promise track record versus actual delivery could not be assessed as previous quarters' call transcripts were unavailable. (answer expected in: Q3 FY26 and Q1 FY27 earnings call transcripts or investor presentations)
- Exact breakdown of project-level land configuration, DC/AC capacity, and partial commissioning status for operational tracking. (answer expected in: Next quarter's investor presentation (Q3 FY27 investor deck))
- Quarterly trajectory of power purchased from external exchanges (IEX) versus internal solar generation for BESS charging. (answer expected in: Q3 FY27 earnings call presentation and operational updates)
- Final H2 FY27 capex cash outflow and total capitalization schedule across solar modules and 5 GWh pending battery deliveries. (answer expected in: Q3 FY27 financial results filing and balance sheet notes)
Frequently asked questions
What did ACME Solar Holdings management say on the Q2 FY27 call?
Acme Solar Holdings delivered strong operational performance in Q2 FY27, with total revenue rising 67.5% YoY to ₹1,007 crore and EBITDA expanding 63.6% YoY to ₹874 crore at an 86.7% margin. Net profit increased 133.5% YoY to ₹269 crore. Growth was driven by short-term BESS peak power monetization and 19.6% higher generation output (1,840 MU). BESS capacity reached 5.2 GWh,…
What guidance did ACME Solar Holdings give?
BESS Commissioning Target: >12 GWh for FY2027.
Is this a recommendation?
No. FinMinutes reports what was filed and said, and the questions it raises. It does not recommend buying, selling or holding any security.
The full ACME Solar Holdings Q2 FY27 results page →
The ACME Solar Holdings terminal →
Quotes are verbatim from the transcript, presentation or press release named beside them. FinMinutes is a financial data and analytics platform; nothing here is a recommendation to buy, sell or hold any security.


Leave a Reply